Packages 1 and 2 · Address and mail
Just the registered office, or an address with mail and phoneWho is this for?Which option fits?For an address without an office. Package 1 is the registered office; Package 2 adds a mailbox, mail scanning and an AI receptionist. Need an office? Package 3 or 4.
Choose one of the two options
Registered Office
Registered OfficeRegistered OfficeYour Cyprus company's official address under Cap. 113, shown in the company register and on official letters. In other words, its legal home, not an office to work in.
The official address of your Cyprus company, recorded in the company register. No office to work in.
€29/month*
Package 2 includes mail handling and the AI receptionist.
Business Address with mail handling
A business address with your own mailbox. We receive your mail, scan it and make it available to you.
€79/month*
Without mail handling: Registered Office from €29.
Niko explains Package 1 and Package 2AI voice guide0:00Audio coming soon
- Official mail scanningOfficial mailWe receive and scan official mail from authorities and courts. General business mail, parcels and courier deliveries come with Package 2.
- Registered office under Cap. 113Registered office under Cap. 113The formal registered office of your company under Cyprus company law, the Companies Law, Cap. 113. This is the address recorded in the company register.
- Statutory registers kept hereStatutory registersThe registers your company must keep by law are held at this address.
- 2 days on site a monthDays on siteYou can work at the main location on two days a month, from 9:00 to 18:00. Each extra day costs €25; unused days expire at the end of the month.
- Office number in the addressYour office numberYour address always includes the office number assigned to you. A room or desk number and a mailbox of your own are not part of Package 1.
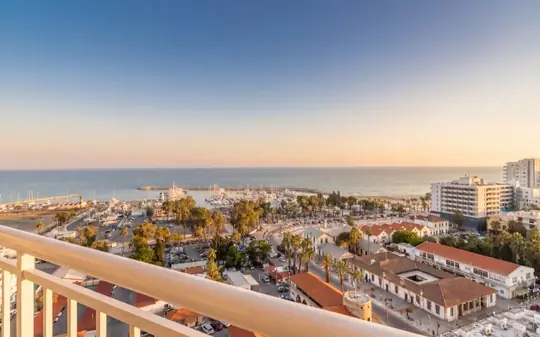
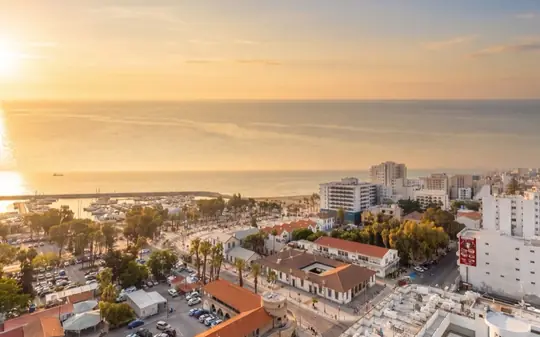
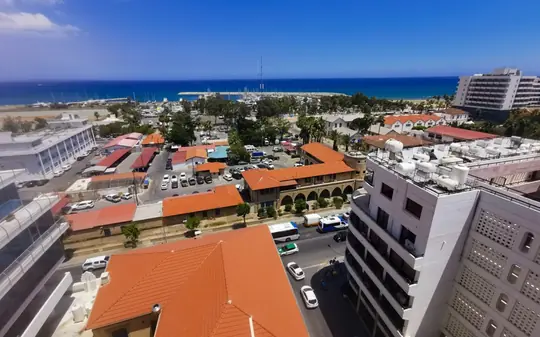
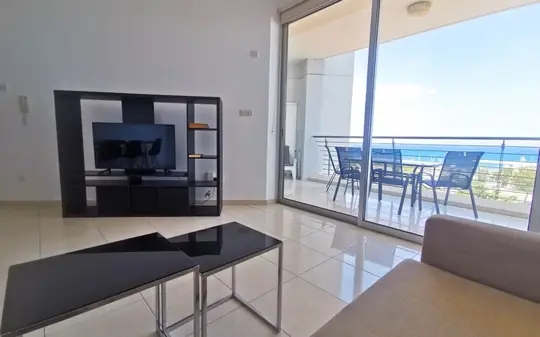
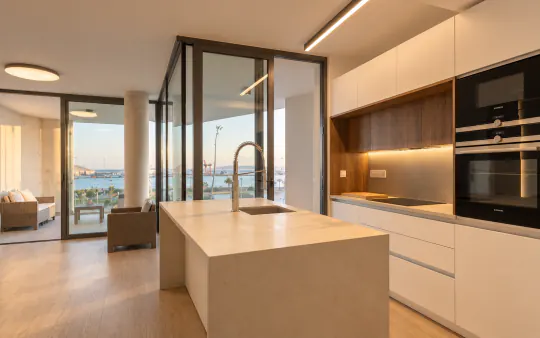
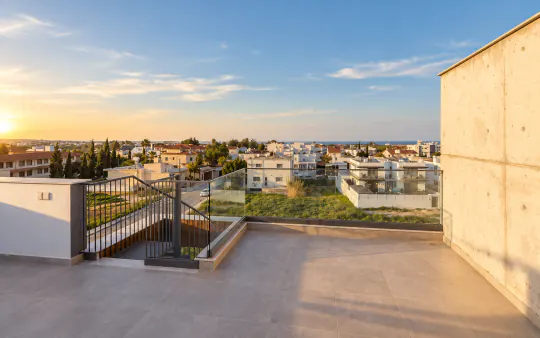
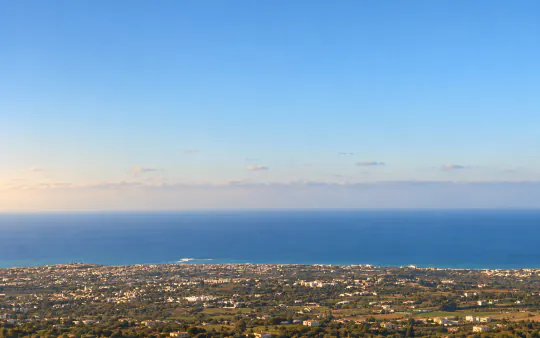
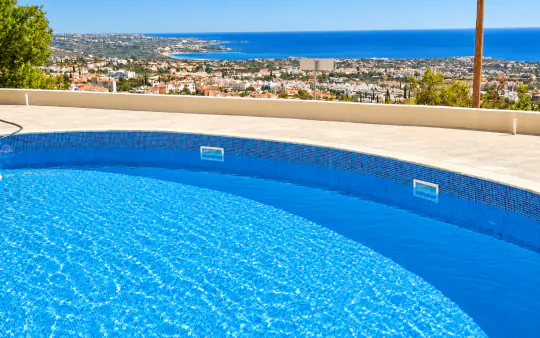
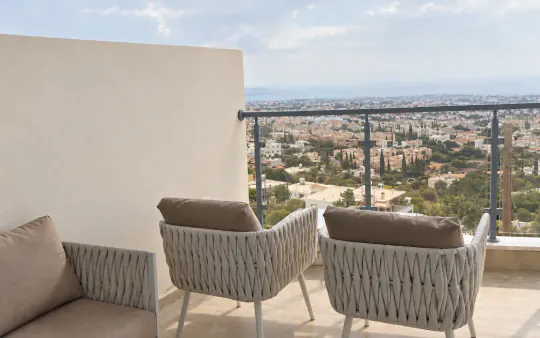
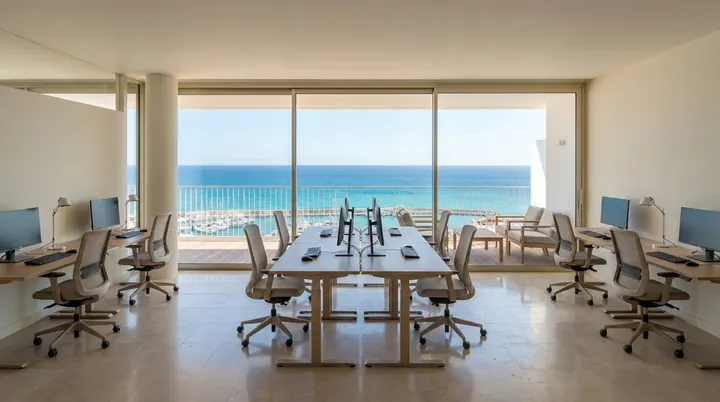
- One of seven locations, assigned subject to availabilitySeven locationsAll in and around Larnaca, including the main location with the sea view; we assign your address subject to availability. Package 4 is only available at the main location.
- No mailbox, no signWhat is not includedNo compartment of your own in the mailbox unit, no company sign on the building, no Google Business Profile, no parcels or courier deliveries. These come with the larger packages.
✓ Suitable forfive items
- A formal registered office without any workspace of your own
- Companies that only need the registered office required by law
- Starting small now and upgrading to a larger package later
- A secondary address alongside a real place where you work
- The register entry plus an address for service of documents
✗ Not suitable forfive items
- Letting your apartment to holiday guests, which needs an officeHoliday rentalIf you let your apartment to holiday guests, your company needs its own office at a different address. A virtual address is not enough, so choose Package 3 or 4.
- A gov.cy registration that requires real business premisesgov.cy (Cyprus) · Companies with Foreign InterestsThis requirement of the Republic of Cyprus applies to registering a company with foreign interests: if you want to employ staff from third countries (outside the EU) through your Cyprus company, you must prove that it has business premises of exactly this kind.Immovable property title/deed or a purchase agreement or rental agreement (at least 12-month duration) for the business premises of the company. Please note that, business premises must be separate from any kind of residence (separate from a shareholder’s residential property).In short: You need a lease or purchase agreement for at least twelve months, with business premises separate from any kind of residential space.Go to the original page (gov.cy/bsc)
- Physical presence as the Central Bank of Cyprus defines itCentral Bank of Cyprus · Directive 2025The Central Bank of Cyprus supervises all Cypriot banks. Under this directive, every bank must check and document whether your Cyprus company has a physical presence before it maintains an account for the company.The physical presence of a company/legal entity is interpreted as the existence of a place of business or activity (owned or rented buildings) in the country of incorporation/registration. [...] The presence of a third person who merely provides the services of a representative/authorised person, including company secretary duties, shall not in itself constitute an indication of physical presence.In short: Physical presence means an owned or rented building in which the company operates. Mere representation and secretarial services are not enough.Go to the original page (centralbank.cy)
- Tax rules that test whether a company has real business premisesUnited Kingdom · HMRC International Manual INTM200810 (CFC business premises condition)HM Revenue & Customs explains to its own staff why a foreign subsidiary must have real premises to escape the UK controlled foreign company charge.The business premises condition requires the CFC to have a physical presence in its territory of residence. This is intended to prevent “brass plate” arrangements from benefitting from the conditions for exclusion. The business premises in the territory have to be in use by the business with a reasonable degree of permanence, or at least be intended to be used in this way in the future. A “reasonable degree of permanence” can be taken for these purposes to mean business premises that will be used for at least 12 months. In addition, those premises need to be the place from which the CFC’s activities in that territory are mainly carried on [...] it needs to be the main place of business in that territory of residence.In short: The UK tax authority says a nameplate at an address is not enough: the company needs premises it actually uses, for at least a year, as its main place of business. This is guidance on one UK rule (an exemption from the UK charge on controlled foreign companies), not a general law for every company. It describes exactly the difference between a registered address and a workplace you really use.Elsewhere in EuropeFrance: tax office looks for premises, staff and equipment, plus real activity Original text (French)Spain: whole profit taxed at home without material and human resources Original text (Spanish)Italy: rule lifted only for real activity with staff, equipment, assets and premises Original text (Italian)Belgium: renting an office and a part time employee is not enough Original text (French and Dutch)Read INTM200810 on GOV.UK
- Tax tests that look for space at your company's disposalOECD · Model Tax Convention on Income and on Capital 2025, Commentary on Article 5, paragraphs 10 to 12The OECD Commentary is the reference text that tax authorities across Europe use to decide when a company has a real place of business, and it explains that this means space the company actually has at its disposal, which may be part of someone else's building or a location shared by several enterprises.10. The term “place of business” covers any premises, facilities or installations used for carrying on the business of the enterprise whether or not they are used exclusively for that purpose. [...] It is immaterial whether the premises, facilities or installations are owned or rented by or are otherwise at the disposal of the enterprise. [...] Again the place of business may be situated in the business facilities of another enterprise. This may be the case for instance where the foreign enterprise has at its constant disposal certain premises or a part thereof owned by the other enterprise.
12. Whilst no formal legal right to use a particular place is required for that place to constitute a permanent establishment, the mere presence of an enterprise at a particular location does not necessarily mean that that location is at the disposal of that enterprise. [...] Where an enterprise has an exclusive legal right to use a particular location which is used only for carrying on that enterprise’s own business activities (e.g. where it has legal possession of that location), that location is clearly at the disposal of the enterprise. This will also be the case where an enterprise is allowed to use a specific location that belongs to another enterprise or that is used by a number of enterprises and performs its business activities at that location on a continuous basis during an extended period of time. This will not be the case, however, where the enterprise’s presence at a location is so intermittent or incidental that the location cannot be considered a place of business of the enterprise [...]In short: A place of business is space a company really has at its disposal and works from on a continuous basis; it does not have to be exclusive, and part of another firm's premises or a location shared by several enterprises can qualify. Being merely present somewhere, or turning up only occasionally, is not enough. The Commentary defines a permanent establishment for tax treaties; it is not a substance test for a company's home country and does not mention registered office addresses as such.Elsewhere in EuropeUnited Kingdom: an office inside another company's premises can be at your disposal Original textCyprus: the registered office is by law the address for official notices Original text (Greek)France: a fictitious registered office is disregarded; the real seat counts Original text (French)OECD Model Tax Convention 2025 (Full Version), Commentary on Article 5, pages C(5)-3 to C(5)-4 (PDF)
- Your own labelled mailboxShared mailbox unitA labelled compartment in the location's mailbox unit. We scan your mail regularly and the scans are ready shortly afterwards. From Package 3, you get a mailbox of your own.
- AI receptionist includedAI receptionistShe answers calls in your company's name. Set-up included, no extra monthly fee: only call minutes, at a price agreed in advance. Try it yourself: +49 158 886 37037.
- 5 days on site a monthDays on siteYou can work at the main location on five days a month, from 9:00 to 18:00. Each extra day costs €25; unused days expire at the end of the month.
- Mail, parcels and courierMail, parcels and courierWe receive and regularly scan your mail and parcels; the scans are ready for you shortly afterwards. We can also sign for courier and registered deliveries and receive bank cards.
- Optional Cyprus landline numberLandline numberYou can add up to two Cyprus landline numbers at €5 a month each; on top of that, only call charges apply. On request, your AI receptionist answers these numbers.
- One of seven locations, assigned subject to availabilitySeven locationsAll in and around Larnaca, including the main location with the sea view; we assign your address subject to availability. Package 4 is only available at the main location.
- No office of your ownNo office of your ownMail handling at a business address: no desk of your own, no lockable office and no Google Business Profile. That is what the office packages are for.
✓ Suitable forfive items
- Call answering without having to employ a receptionist
- One of seven locations, assigned subject to availability
- A delivery address for mail and parcels, with no office space
- A professional mailing address in your company's name
- Official mail scanned for you, without an office of your own
✗ Not suitable forfive items
- A Google Business Profile, which needs real business premises
- Physical presence under paragraph 37(2) of the directiveCentral Bank of Cyprus · Directive 2025The Central Bank of Cyprus supervises all Cypriot banks. Under this directive, every bank must check and document whether your Cyprus company has a physical presence before it maintains an account for the company.The physical presence of a company/legal entity is interpreted as the existence of a place of business or activity (owned or rented buildings) in the country of incorporation/registration. [...] The presence of a third person who merely provides the services of a representative/authorised person, including company secretary duties, shall not in itself constitute an indication of physical presence.In short: Physical presence means an owned or rented building in which the company operates. Mere representation and secretarial services are not enough.Go to the original page (centralbank.cy)
- Letting your apartment to holiday guests, which needs an officeHoliday rentalIf you let your apartment to holiday guests, your company needs its own office at a different address. A virtual address is not enough, so choose Package 3 or 4.
- The gov.cy criteria for clearly designated business premises
- Proof of a real office that a holding company actually usesNetherlands · Uitvoeringsbeschikking dividendbelasting 1965, Article 1bis(h)This Dutch ministerial regulation lists the substance a foreign company must show to be treated as having genuine business reasons when it receives Dutch dividends, and one item on that list is a real office that is actually used.[...] wordt geacht sprake te zijn van geldige zakelijke redenen die de economische realiteit weerspiegelen indien: [...] h. de opbrengstgerechtigde gedurende een periode van ten minste 24 maanden een in de staat, bedoeld in onderdeel a, gelegen onroerende zaak of deel van een onroerende zaak ter beschikking heeft waarbij zich in die onroerende zaak, onderscheidenlijk dat deel, een kantoor bevindt dat is voorzien van gebruikelijke faciliteiten voor de uitoefening van de werkzaamheden, bedoeld in onderdeel g, en die werkzaamheden ook daadwerkelijk in dat kantoor worden uitgeoefend.
Our own translation: [...] valid business reasons that reflect economic reality are deemed to exist if: [...] (h) for a period of at least 24 months the recipient of the income has at its disposal immovable property, or part of immovable property, located in the State referred to in (a), in which property, or in which part, there is an office equipped with the usual facilities for carrying out the activities referred to in (g), and those activities are also actually carried out in that office.In short: Our own translation: the recipient must have at its disposal a building or part of a building with a normally equipped office for at least 24 months, and the work must actually be done in that office. The Dutch text treats part of a building as enough, but only if the office is really used; a registered address alone does not meet it. It is one item on a cumulative list (local directors, staff, bank accounts, books, wage costs of at least EUR 100,000 times a country factor), so it is stricter than an office package on its own.Elsewhere in EuropeOECD and G20: letter box and brass plate companies cannot claim holding company regimes Original textEuropean Union: dividend benefits refused where arrangements do not reflect economic reality Original textLuxembourg: financing companies need a real presence, qualified staff and local decisions Original text (French)Cyprus: residence certificate only if management and control are exercised in Cyprus Original text (Greek)Read Article 1bis on wetten.overheid.nl (Dutch government law database)